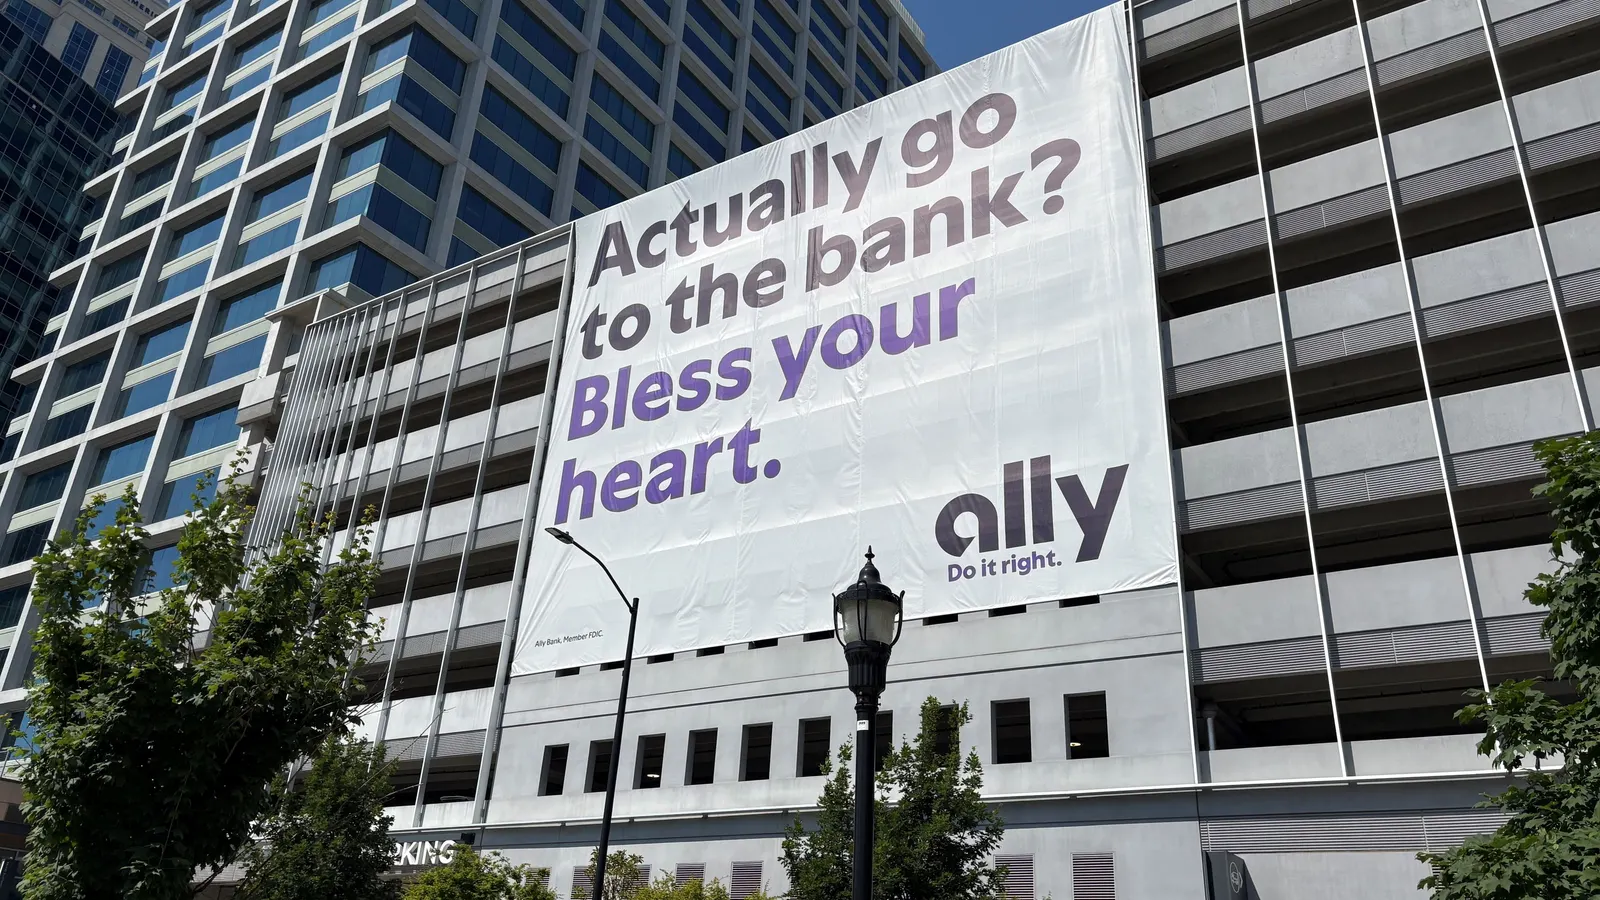

Ally Financial processed a record 4.8 million auto credit applications in the third quarter, up 20% from a year ago. Many of those applications were never meant to be approved.
The former General Motors captive finance arm has spent two years asking dealers to send every credit application through its system, regardless of whether the borrower meets Ally’s standards. The rejects get referred to partner lenders for a fee. The real prize, according to CEO Michael Rhodes, is the data.
Analyzing that flood of applications lets Ally spot lending segments worth pursuing or dodging, and reprice its loans on the fly. It is a strategy that turns rejection into intelligence.
Consumer auto originations hit $12.9 billion for the quarter, a 10% jump year-over-year in a market that is flat to slightly down. Net income attributable to common shareholders rose 8% to $401 million. Those are real numbers in a lending environment that has humbled plenty of competitors.
Ally’s dealer network, 21,400 strong as of late 2025, still skews heavily toward GM and former Chrysler stores. That legacy relationship matters. CFO Russ Hutchinson called it out explicitly on the earnings call.
“They have rewarded us through application flow,” he said, the kind of understatement that means dealers are routing business Ally’s way because they trust the company to say yes more often than the next bank.
Rhodes framed the quarter as vindication. “We have made deliberate choices about where to invest and grow, and our results reinforce that we are on the right path,” he told analysts. Those deliberate choices included exiting consumer mortgages and dumping the credit card business last year.
What remains is a tightly focused operation: auto lending, insurance products like extended warranties and GAP coverage, dealer floorplan financing, the SmartAuction wholesale platform, and Ally Bank’s online consumer deposits.
Strip away the optimism, though, and some cracks showed.
Lease returns from Stellantis dealers hit Ally with an average loss of $914 per vehicle in the quarter. A year earlier, Ally was making $53 per return. Recall-affected vehicles were the culprit, and management expects the pain to linger through the fourth quarter before easing in 2027.
The volume of returns actually dropped, from 21,608 to 17,494, but the per-unit losses more than wiped out that benefit.
Delinquencies ticked up too. The 30-plus-day delinquent rate climbed to 4.96% from 4.9% a year ago. Hutchinson traced the softness to loans originated in late 2025 and early 2026.
He was careful not to sound alarmed. “Nothing we are seeing gives us a ton of concern right now,” he said, adding that underwriting adjustments happen in real time.
That language is worth reading closely. A lender that adjusts underwriting in real time is a lender that sees something moving. The question is whether the pass-through strategy, which floods the system with data from borrowers who don’t qualify, is helping Ally catch those shifts faster than rivals, or whether the sheer volume creates its own blind spots.
Ally has turned itself into a data-harvesting operation that happens to make car loans. Every rejected application feeds the machine. Every fee from a referred deal adds margin.
The model works beautifully when credit conditions are stable. The third quarter suggests conditions are starting to shift, even if only at the margins.
Ally says it is watching closely. Given that its entire competitive edge depends on reading the data better than anyone else, it had better be.
Share this Story